
When people think about wealth, they often focus on net worth. Net worth is the value of everything you own after subtracting everything you owe. When assessing net worth in Singapore, this figure is useful for measuring accumulated wealth, but it does not tell you how easily that wealth can support your everyday expenses.
Cash flow tells you something different. It tracks the money coming into and going out of your finances over time. You could have a net worth of more than S$1 million and still struggle to pay next month’s bills. Someone with a much lower net worth may be more financially stable day to day simply because they have healthy, consistent cash flow.
Both matter, particularly in Singapore, where property ownership and CPF savings can make up a substantial share of your wealth on paper.
Key takeaways
- Net worth measures the value of your assets less your liabilities, while cash flow tracks the money coming into and going out of your finances.
- In Singapore, a high net worth can be misleading when much of it is tied up in property and CPF savings that are not easily converted into cash.
- Being asset-rich but cash-poor can leave you financially vulnerable even when your net worth appears substantial on paper.
- Cash flow helps you manage everyday expenses, build emergency savings, and maintain financial stability during periods of uncertainty or retirement.
- Net worth provides an indication of long-term wealth accumulation and progress towards financial goals, but it should not be viewed in isolation.
- Liquidity shows how much of your wealth you can access relatively quickly when you need money.
- A strong financial position combines a growing net worth with healthy cash flow and sufficient liquidity.
What is net worth?
For anyone asking what is net worth, it is the total value of everything you own after subtracting everything you owe. Think of it as a snapshot of your overall financial position at a particular point in time.
The calculation is straightforward: Net worth = Total assets − Total liabilities
Assets that may contribute to your net worth include:
- Property
- CPF balances
- Cash and savings
- Investments such as shares, ETFs and unit trusts
- Vehicles and other valuable possessions
Liabilities that reduce your net worth include:
- Outstanding mortgage loans
- Car loans
- Personal loans
- Credit card debt
If your assets are worth $2 million and your total debts amount to $600,000, for example, your net worth is $1.4 million. This figure brings your accumulated assets and outstanding debt together in a single measure. As a general rule, a growing net worth indicates that you are accumulating wealth over the long term.
What is cash flow?
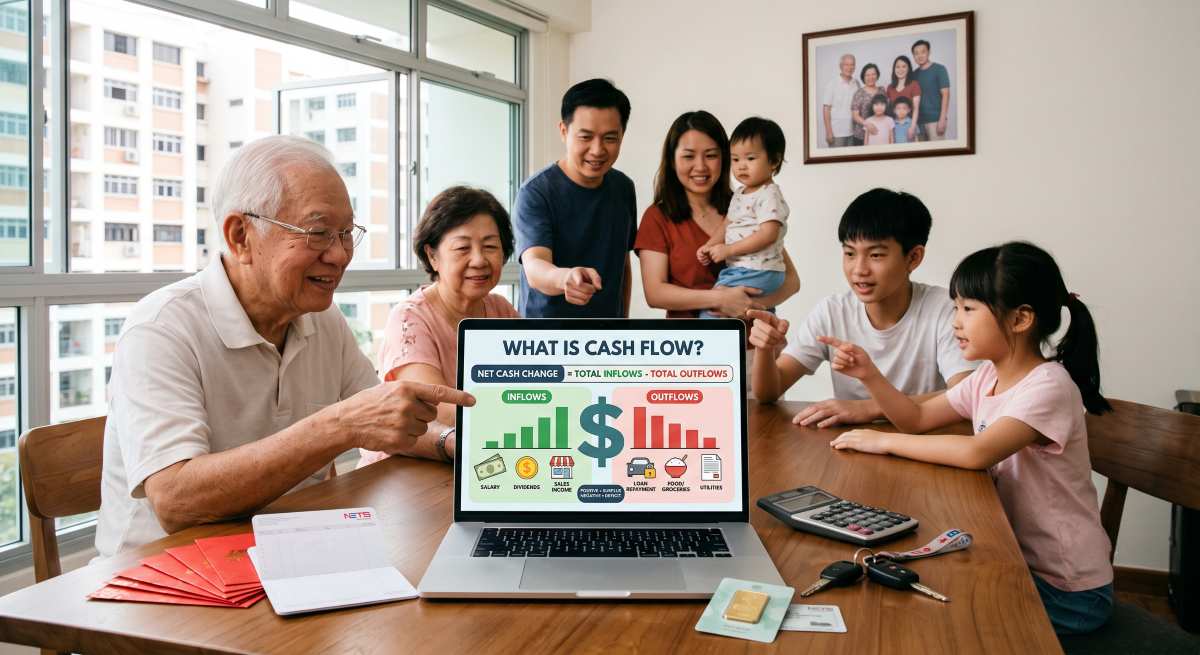
Cash flow refers to the money coming into and going out of your finances over a period of time, usually each month. Net worth measures accumulated wealth, while cash flow shows whether your current income can support your spending and financial commitments.
Cash flow can be positive or negative:
- Positive cash flow means you earn more than you spend.
- Negative cash flow means your expenses exceed your income.
Common cash inflows include:
- Salary
- Rental income
- Dividends
- Business income
- Interest from savings or investments
Common cash outflows include:
- Mortgage repayments
- Household bills
- Insurance premiums
- Groceries
- Transport
- Entertainment and lifestyle expenses
Cash flow gives you a more immediate picture of your finances than net worth. Healthy cash flow allows you to pay bills, build savings, and invest consistently without relying on debt.
Read more: What You Need to Know About Active vs Passive Income
Difference between net worth and cash flow
Net worth and cash flow are closely related, but they measure different things. Net worth focuses on accumulated assets and liabilities. Cash flow focuses on the movement of income and expenses.
| Net worth | Cash flow |
| Measures accumulated wealth | Measures money moving in and out |
| Provides a snapshot at one point in time | Provides an ongoing measure of financial health |
| Focuses on assets and liabilities | Focuses on income and expenses |
| Indicates long-term financial progress | Indicates short-term financial stability |
You can think of net worth as your financial balance sheet and cash flow as your monthly budget. One shows what you own after accounting for debt. The other shows how comfortably your income supports your lifestyle.
Why liquidity is the missing piece in your financial picture
Liquidity refers to how quickly and easily an asset can be converted into cash without losing significant value. It connects net worth with cash flow because it shows how much of your accumulated wealth is readily available when you need money.
Some assets are highly liquid, including:
- Cash
- Savings accounts
- Money market funds
Others are less liquid, including:
- Property
- CPF balances
- Private business interests
- Certain investments
Consider two people who each have a net worth of $2 million. The first owns a valuable property but has very little cash. The second holds most of their wealth in cash, savings, and readily sellable investments.
Their net worth is identical, but the second person can access a much larger share of their wealth at short notice without selling a home or accepting a fire-sale price. That difference in accessibility is what liquidity measures.
Liquidity gives you financial flexibility. Having accessible funds means you have more options when unexpected expenses or changes in circumstances arise.
Read more: How Much Cash Should You Keep in the Bank
Why net worth in Singapore figures can be misleading
A net worth in Singapore figure does not always reveal how financially flexible someone is. Property and CPF savings can represent a significant share of a person’s assets, but that money may not be readily available when cash is needed.
Consider someone who owns the following assets:
- A condominium worth $1.8 million
- CPF savings of $450,000
- Investments worth $150,000
- Cash savings of $20,000
Their assets total $2.42 million.After deducting an outstanding mortgage of $900,000, their net worth is around $1.52 million. Yet they have only $20,000 in readily available cash.
The value locked inside their property cannot be used for monthly expenses unless they sell, refinance or monetise it. CPF savings are also meant primarily for retirement, housing and healthcare. Before age 55, they generally cannot be withdrawn as cash. From age 55, you can only withdraw savings above your Retirement Account requirement or a minimum of S$5,000, so much of the balance remains set aside for future retirement payouts.
A high net worth, in other words, does not automatically give you financial flexibility.
What average net worth in Singapore figures may not show
An average net worth in Singapore figure can provide a reference point for accumulated wealth, but it does not reveal how that wealth is divided between liquid and illiquid assets. Two people with the same net worth may have very different amounts of cash available to them.
Net worth is more useful when you consider it alongside cash flow and liquidity rather than treating it as a standalone measure of financial security.
Read more: Are You Financially Healthy in Singapore? Income, Savings & Debt
The asset rich cash poor Singapore trap
The asset rich cash poor Singapore situation occurs when someone has substantial wealth, but most of it is tied up in assets that are difficult or costly to convert into cash. Their balance sheet may look strong even though they have limited ability to handle immediate expenses.
Common examples of becoming asset-rich but cash-poor include:
- Owning an expensive home while struggling with monthly mortgage repayments.
- Investing heavily while keeping very little emergency savings.
- Having substantial CPF balances but limited cash for unexpected expenses.
Someone in this position may appear financially secure on paper. A sudden retrenchment, medical emergency, or economic downturn could still put significant pressure on their finances.
Without sufficient cash reserves, they may have to:
- Sell investments at an unfavourable time.
- Borrow money at high interest rates.
- Dip into long-term savings.
- Delay important financial goals.
Wealth on paper offers limited short-term flexibility if you cannot access the money when you need it.
When cash flow matters more
Cash flow becomes especially important when you have immediate financial obligations that depend on regular, accessible income. It determines whether you can meet recurring expenses without selling assets or taking on more debt.
Healthy cash flow is especially important when you are:
- Paying monthly household expenses
- Supporting children or ageing parents
- Building an emergency fund
- Running a business
- Coping with variable income
- Planning for retirement income
Good cash flow gives you room to deal with unexpected expenses without disrupting your wider financial plans. It also makes it easier to continue saving and investing towards longer-term goals.
For retirees, cash flow often becomes a central concern. They may have accumulated significant wealth over the years, but they still need reliable income to cover everyday living expenses.
Building passive income Singapore streams
Passive income Singapore strategies can form part of a broader approach to strengthening cash flow. Income from sources such as dividends or rental property may supplement other inflows and help cover regular expenses.
Multiple income streams are not only about increasing net worth. They can also improve cash flow and reduce your dependence on a single source of earnings.
When net worth matters more
Net worth becomes more useful when you want to measure long-term financial progress. Cash flow tells you whether your current income supports your expenses. Net worth shows how your accumulated assets and liabilities are changing over time.
Tracking net worth can help you assess:
- Whether your wealth is increasing over time
- Whether your debt is reducing
- Whether your saving and investing are building assets
- Whether you are progressing towards retirement goals
- How close you are to financial independence
Someone with a consistently increasing net worth is generally building wealth through saving, investing, and debt repayment.
Net worth is also useful when looking at your overall financial resilience and planning major long-term goals such as retirement or leaving a legacy for your family.
How to balance net worth, cash flow, and liquidity
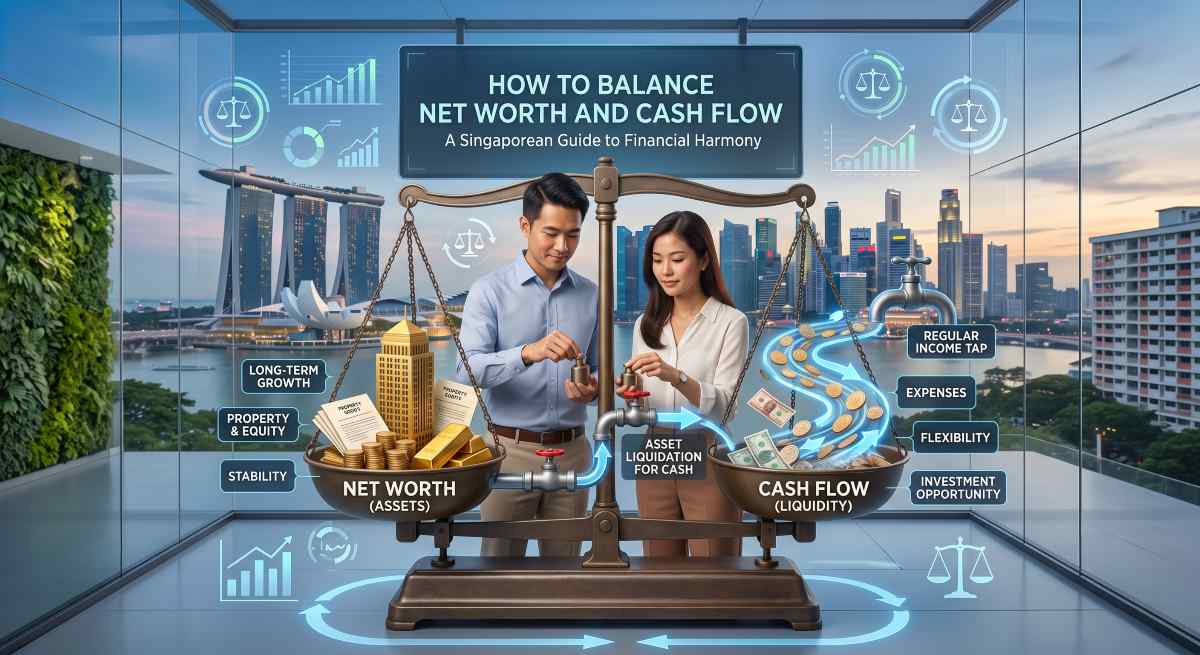
A balanced financial position considers net worth, cash flow, and liquidity together. Looking at only one of these measures can hide weaknesses elsewhere in your finances.
Practical ways to balance these three areas include:
- Build an emergency fund covering at least three to six months of living expenses.
- Avoid putting too much of your wealth into illiquid assets.
- Invest consistently to grow your long-term net worth.
- Create multiple income streams, such as dividends or rental income.
- Review your monthly cash flow regularly to ensure your spending remains sustainable.
- Track your net worth annually to monitor your overall financial progress.
The aim is not simply to become wealthier on paper. You also want enough accessible money to meet current needs while continuing to build wealth over time.
Understanding how net worth, cash flow, and liquidity fit together is easier once the fundamentals are in place. If you want to build that foundation, Planner Bee’s finance basics guides walk through budgeting, saving, debt, and the core concepts behind money management in Singapore.
Read more: Financial Planning Checklist Singaporeans Need Before 40
Conclusion
For net worth in Singapore, the headline figure only tells part of the story. A growing net worth matters for long-term wealth, but it is far less useful if you struggle to meet current expenses or cannot access enough of that wealth when you need it.
Cash flow and liquidity fill in those gaps. Together with net worth, they give you a more practical picture of your financial position and whether the wealth you have built can support both your current needs and longer-term goals.
Frequently asked questions
What is net worth and how do I calculate it?
Net worth is the value of all your assets minus your total liabilities. Add up assets such as property, CPF savings, cash and investments, then subtract debts such as mortgages, loans and credit card balances.
Is a high net worth the same as being financially secure?
No. A high net worth may include assets such as property and CPF savings that are not readily available as cash, so cash flow and liquidity also matter.
Is cash flow more important than net worth?
Cash flow is more important for meeting current expenses, while net worth is useful for tracking long-term wealth. A healthy financial position generally requires both.
Does CPF count towards net worth in Singapore?
CPF balances can be included as part of your assets when calculating net worth. They are less liquid than cash because withdrawals are subject to CPF rules and are intended primarily for retirement, housing and healthcare.
Why is liquidity important when measuring financial health?
Liquidity shows how easily you can access money without having to sell an illiquid asset or accept a significant loss in value. Having sufficient liquidity can help you manage emergencies and unexpected expenses.